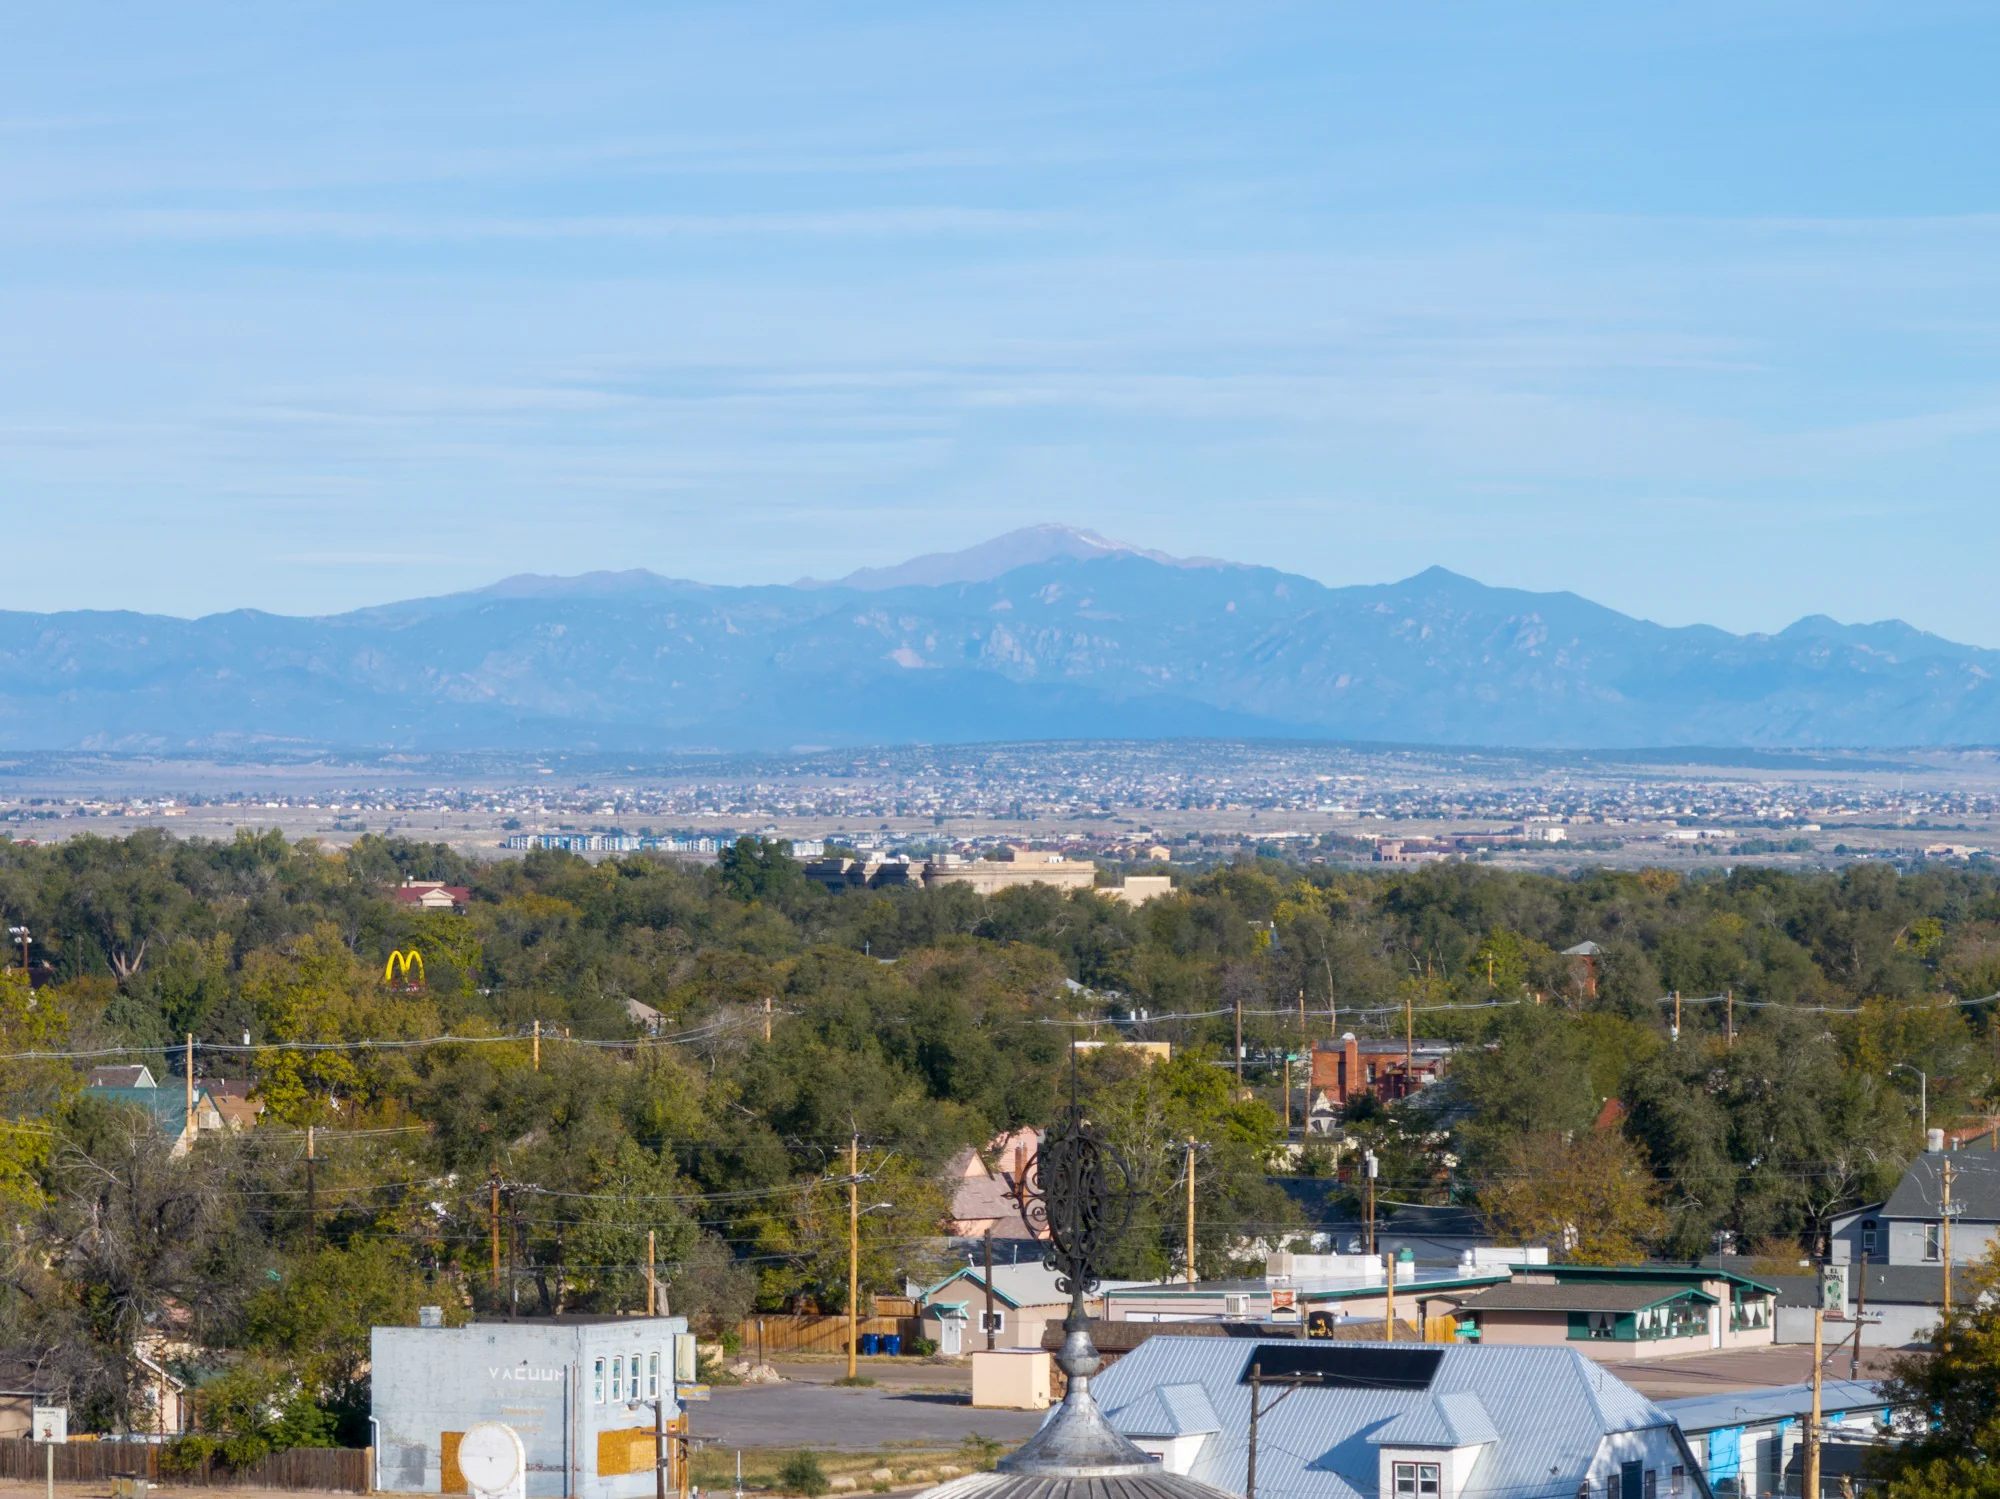
Pikes Peak beyond Pueblo
Planning your purchase
How much house can I afford?
Start with a payment that fits your life.
Read the guide
The Steel City learning center
Good questions. Plain answers.
Start with the questions most buyers ask. Each guide is a starting point for a more personal conversation.
Pikes Peak beyond Pueblo
Planning your purchase
Start with a payment that fits your life.
Read the guide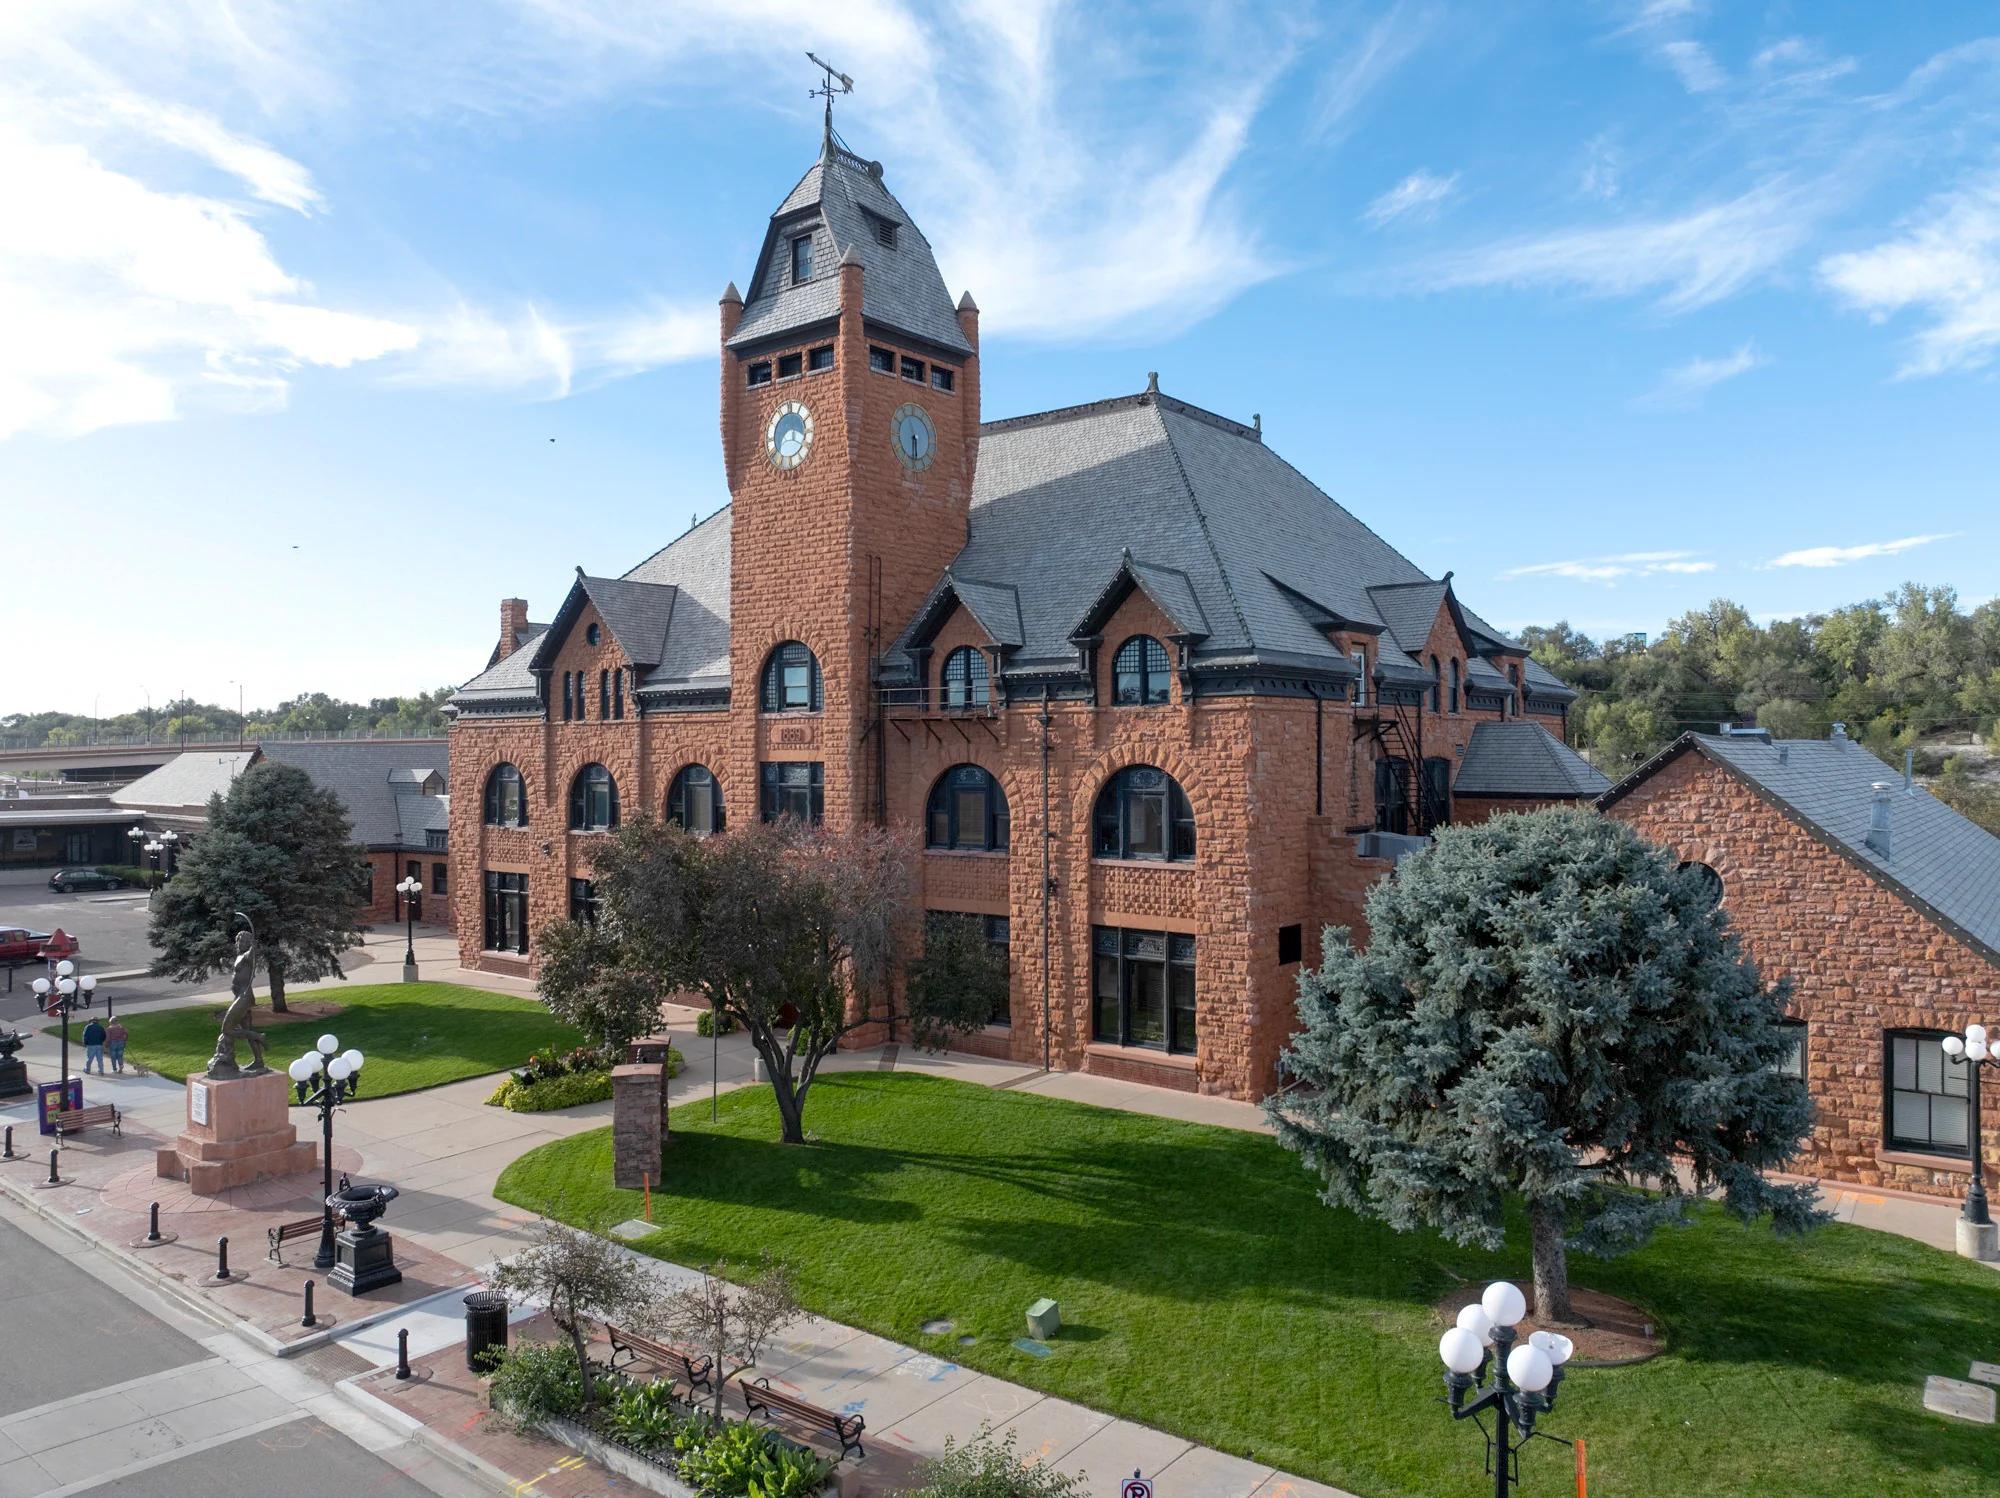
Union Depot · Pueblo
Getting ready
Understand the difference before you start looking.
Read the guide
Pueblo steel mill
Exploring your options
What to ask about assistance programs.
Read the guidePut it into perspective
More to explore
FHA loans are insured by the government and are more forgiving on credit and down payment, but they carry mortgage insurance that often lasts for the life of the loan. Conventional loans ask for stronger credit, and their mortgage insurance can be removed later. The better choice depends on your credit, your down payment and how long you plan to stay.
Read the guideA renovation loan combines the cost of a home and the cost of repairs into one mortgage. The loan amount is based on what the home should be worth once the work is done. At closing the repair money is set aside, and the contractor is paid in stages as the work is completed and inspected.
Read the guideA divorce decree can assign the house to one spouse, but it does not change the mortgage. Both people stay responsible for the loan until it is paid off or refinanced. To keep the home in one name, that spouse usually has to qualify for a new loan alone, and may need to pay the other their share of the equity.
Read the guideClosing costs are the fees and prepaid expenses due when a home loan is finalized, on top of the down payment. They include lender charges, the appraisal, title insurance and settlement fees, government recording fees, and the first deposits for property taxes and homeowners insurance. You receive an itemized estimate soon after you apply.
Read the guideAfter you apply, you receive a Loan Estimate, your documents are reviewed, and an appraisal is ordered. An underwriter then checks the file against the loan program’s rules and may ask for more information. Once the conditions are met you get final approval, review a Closing Disclosure, and sign at closing.
Read the guide
Colorado, called home.
A home. A plan. A conversation that puts you first.
Let’s talk